Retirement planning

The years right before retirement decide a lot
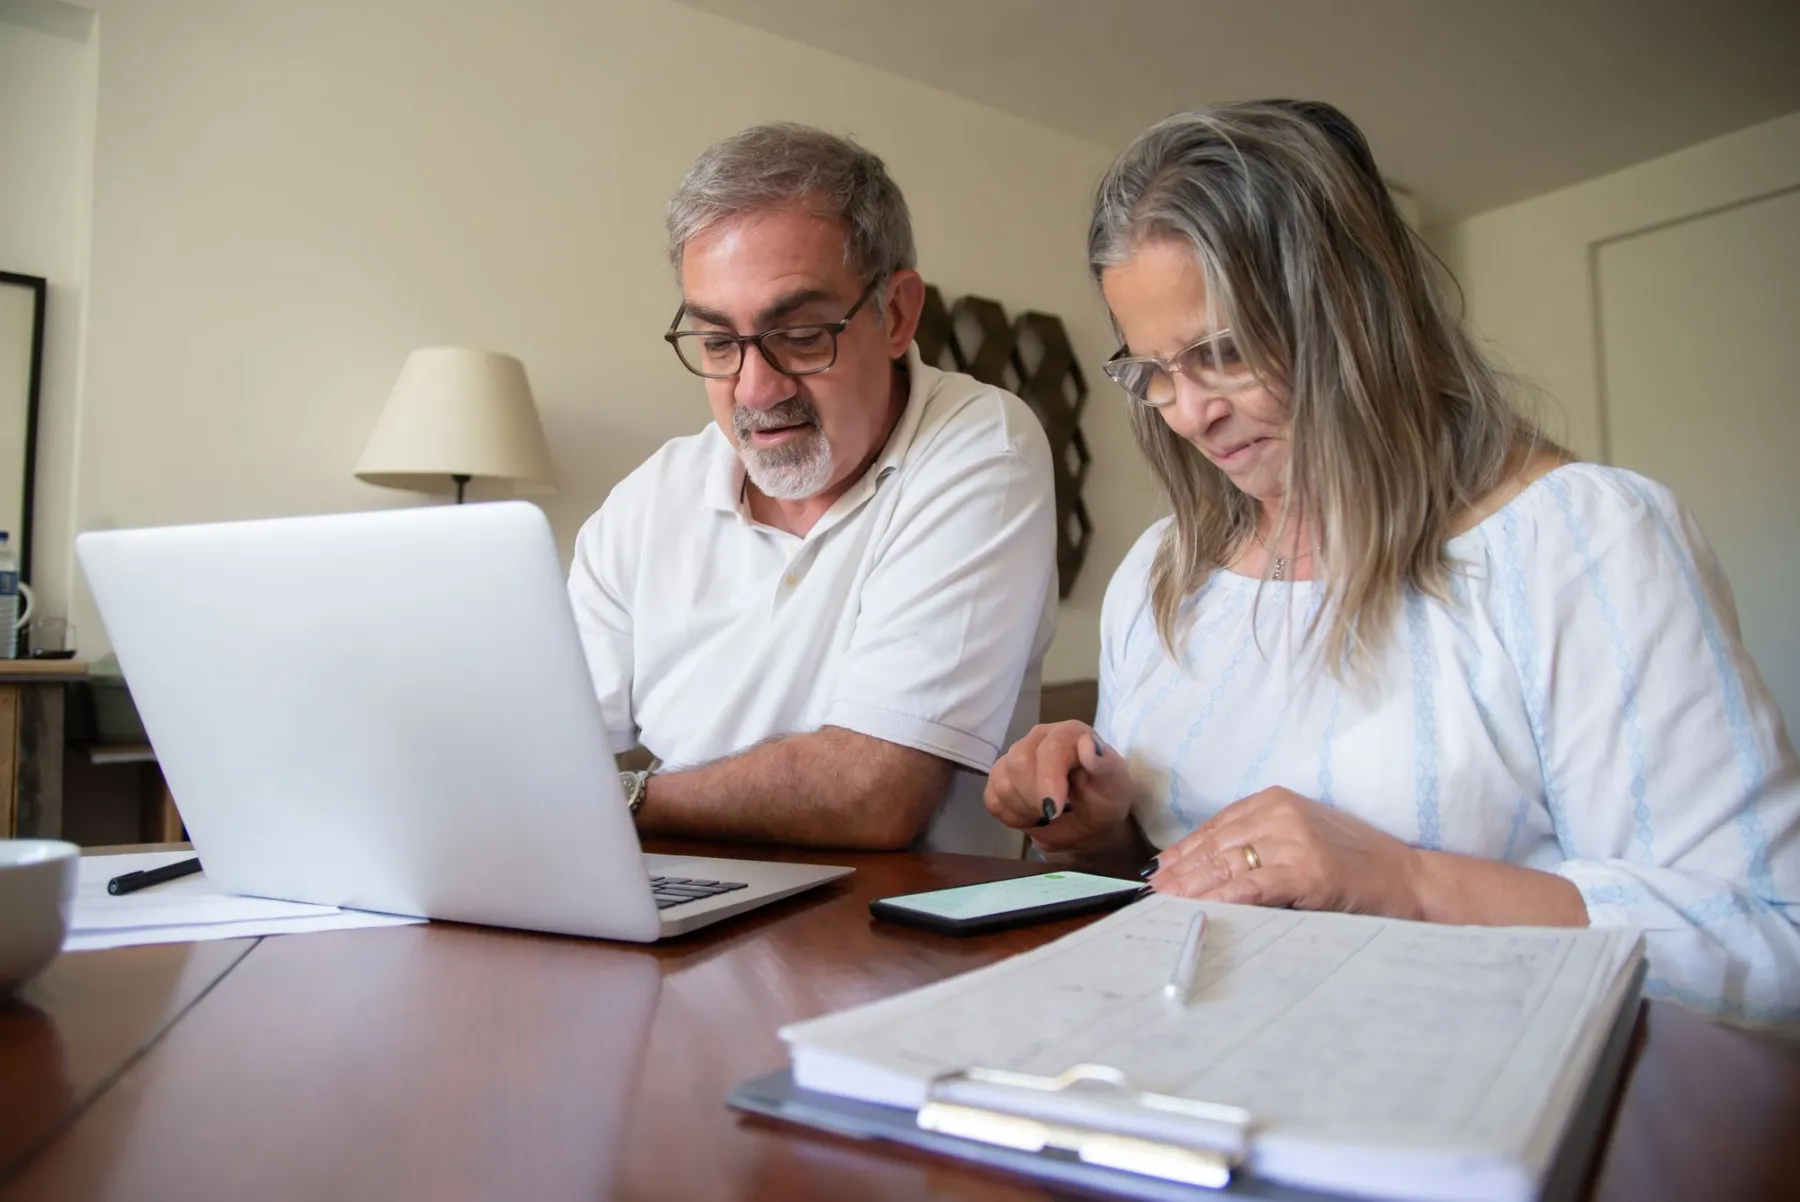
A couple in their sixties working through papers together at a desk with a laptop

Three to five years out is when the biggest choices are still open: when to stop working, when to file for Social Security, how to handle healthcare before Medicare, and where the first years of income will come from. We help you make them in order.

Saving and spending are different skills

For decades the job was to put money in and leave it alone. Retirement reverses the direction, and the habits that built the savings do not tell you how much to take out, from which account, or what to do when the market drops in the same year you retire. Retirement planning is the work of answering those questions before the paycheck stops.

What we work through together

  • Your retirement date, and whether a phased exit from work changes the picture
  • What you actually spend now, and what you expect to spend in the first years of retirement
  • Your Dignity Floor and Dream Tier, which become the targets for the income plan
  • Social Security timing for you and your spouse
  • Healthcare coverage before and after Medicare
  • Pension elections, if you have one
  • Which accounts the first years of income come from, and in what order

Each answer feeds the Reliable Retirement Income Plan, which is where the pieces become a paycheck.
How the income plan works

If you retired recently

Most of these choices are still open in the first two or three years of retirement, and some, such as how withdrawals are sequenced, are worth revisiting right away. A conversation now is the same conversation, with more real numbers in it.

Start the planning before the date is set

The earlier the conversation, the more options are still on the table. There is nothing to decide at the end of the first one.

Cookies and analytics

We use analytics cookies to see which pages are useful. Nothing is shared with advertisers unless you allow it. Privacy policy